12 Ipon Tips to Think Like an Iponista (Small Habits, Real Savings)
An iponista isn't someone who earns a lot. It's someone who decides where money goes before it disappears. Twelve small habits to start this week.
 By the Iponista team · August 25, 2026 · 6 min read
Every barkada has one: the friend who somehow still has money two days before payday, the one who says "sige, next time" to the fifth milk tea of the week. Call them an iponista, and mean it as a compliment. An iponista doesn't need a big salary. They just decide where money goes before it quietly disappears. These ipon tips are the small, repeatable habits that make that possible, even on an ordinary Filipino sahod.
You don't need all twelve. Pick two or three that fit your life and start this week.
What is an iponista, really?
Ipon means saving. The "-ista" makes it an identity, like barista or fashionista. An iponista is someone who treats saving as a skill they're proud of, not a punishment.
That shift matters. When saving is who you are rather than something you "should" do, choices get easier. Skipping an impulse buy doesn't feel like losing; it feels like winning a small round. And that's the whole idea behind this blog, our app and our mascot, Ponpon: making saving feel good instead of guilty.
Payday ipon tips
1. Save first, spend the rest
The single most important habit. Move your ipon the day your sahod lands, before a single purchase. Even ₱200 per kinsenas builds the muscle. We explain the full method in how to save money on a regular sahod.
2. Give every payday a plan
Before spending, write what this cutoff must cover: bills due before the next payday, savings, then daily money. Our kinsenas budgeting guide walks through it step by step.
3. Have a "not yet" list
When you want something that isn't urgent, add it to a list with the date. Look again after two paydays. You'll be surprised how many things you no longer want.
Everyday ipon tips
4. Know your daily number
Divide what's left for spending by the days until your next payday. That's your daily allowance. Checking it takes a few seconds and prevents the end-of-cutoff scramble.
5. Log it the moment you spend it
Awareness is half the battle. Logging "fishball 30 cash" right after buying makes small spending visible. In Iponista, you can type it like a text message and it fills in the amount, category and wallet.
6. Shop the palengke with a list
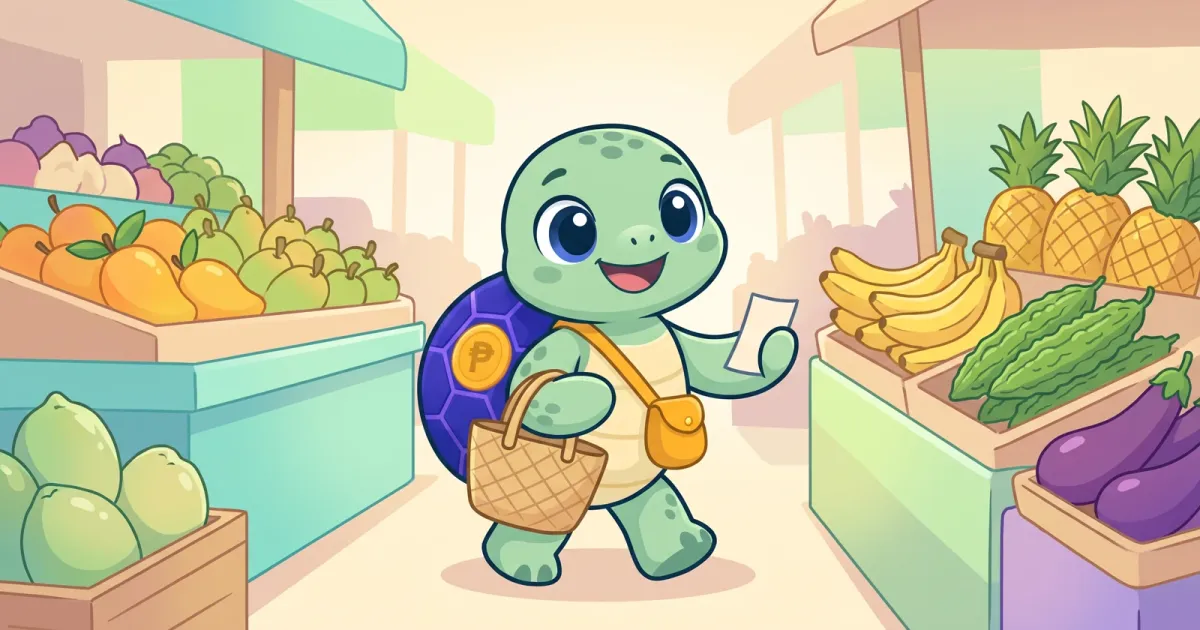
Going to the market without a list is how ₱500 becomes ₱900. Write what you need, bring a bayong, and buy what's in season. It's often fresher and cheaper too.
7. Compare per piece, not per pack
At the grocery or sari-sari store, the bigger pack isn't always cheaper per piece, and the tingi option isn't always more expensive. Quick math before buying adds up over a year.
8. Make baon your default
You don't have to bring lunch every day. Even three days a week makes a difference. Our baon budget guide has realistic ideas for busy people.
Mindset tips for iponistas
9. Separate needs from wants, then enjoy the wants
A needs-and-wants check before buying isn't about banning fun. It's about spending on the things you actually enjoy. We made a quick test for it in needs and wants: a 10-second check.
10. Say no kindly, and without long explanations
Pressure to spend often comes from people we love: a barkada outing, a relative asking for help, a party. "Hindi muna ako this time, pero next month sama ako" is a complete answer. If you're the main earner at home, the breadwinner squeeze lesson has more on setting kind limits.
11. Watch out for scams dressed as opportunities
"Double your money in a month" is never real. Before joining any investment, check the advisories from the Securities and Exchange Commission and read our lesson on how to spot investment scams. A true iponista protects ipon before growing it.
Build-your-future tips
12. Build a cushion before anything else
Before investing or upgrading your phone, build an emergency fund of at least one month of basic expenses. It's the difference between a bad week and a new loan. Our emergency fund lesson explains how much is enough for your situation.
What one cutoff with these ipon tips can look like
Here's an example of how a few of these habits combine, for someone taking home ₱9,000 per kinsenas. It's an illustration, not a rule.
On payday, ₱450 goes straight to a separate savings account (tip 1). Bills due before the next sahod, internet and a share of the rent, are set aside first (tip 2). That leaves about ₱5,500 for 15 days, so the daily number is roughly ₱360 (tip 4).
In the first week, they bring baon three days (tip 8), which frees up money for Friday dinner with friends without going over. A pair of shoes goes on the "not yet" list instead of into the cart (tip 3). On the weekend, the palengke run sticks to the list (tip 6).
By the next payday, nothing dramatic has happened. No extreme sacrifice, no crying over spreadsheets. But the savings account has ₱450 more, the bills are paid, and there's even a small amount left in the wallet. That quiet, boring result is exactly what an iponista is after. Repeat it for a year and it stops being boring.
Common mistakes when you start saving
- Going too hard, too fast. Cutting everything fun in week one usually ends in a big "reward" splurge in week three. Start small.
- Saving in the same wallet you spend from. If the ipon sits next to your daily money, it will get used. Keep it separate.
- Waiting for a raise to start. A bigger salary rarely fixes spending habits on its own; spending tends to rise to meet it. Our guide to lifestyle inflation explains why. Starting with a small amount now is what makes a future raise actually count.
- Comparing with others. Someone else's ₱50,000 savings post says nothing about their rent, family or income. Compare with your own last month.
- Ignoring utang. If you carry credit card debt, paying it down is part of saving. Interest on unpaid balances grows faster than most savings accounts, as our lesson on credit card minimum payments shows.
Becoming an iponista, one payday at a time
Nobody becomes an iponista in a day. You become one payday by payday: one saved amount, one skipped impulse buy, one bill paid on time. Some cutoffs will go wrong. That's fine. The people who end up with real savings don't quit after a bad month; they just start again on the next sahod.
If you want a companion for it, Iponista the app was built exactly for this: fast logging, kinsenas budgets, savings goals with progress rings, and Ponpon's daily notes on your own spending. It's free, works offline and never asks for your bank password. You can also take the short courses in the Iponista Academy and earn your Certified Iponista certificate.
Pick two of these ipon tips, try them for one cutoff, and start tracking free. Want a structured goal? Try one of our ipon challenge ideas.
This article is for education and general guidance, not personal financial advice.
Frequently asked questions
What does iponista mean?
Iponista comes from 'ipon', Filipino for saving, and '-ista', like in barista or fashionista. An iponista is someone who saves on purpose and takes pride in it.
How can I start saving if I have a small salary?
Start with a tiny, fixed amount every payday, like ₱200, and move it before you spend. The habit matters more than the amount at the start.
Is it okay to spend on things I enjoy?
Yes. Saving isn't about never enjoying money. It's about choosing what's worth it to you and cutting the spending you don't even notice.
What's the best first ipon goal?
A small emergency fund, ideally one month of basic expenses. It stops surprise costs from turning into new utang.